Actual Cash Value vs. Replacement Cost: What’s the Difference?

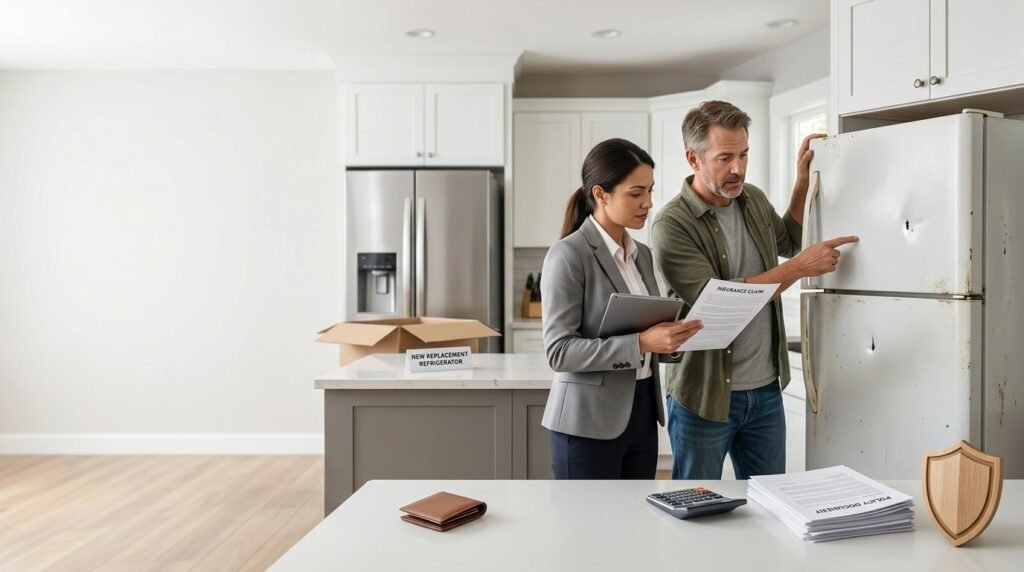
When you buy homeowners or renters insurance, one of the most important questions is how your property will be valued if you have a covered loss.
Two terms you may encounter are Actual Cash Value (ACV) and Replacement Cost Value (RCV).
They sound similar, but they can produce very different claim payments.
The basic difference is this:
Actual Cash Value generally accounts for depreciation.
Replacement Cost generally pays the amount needed to repair or replace covered property with materials or items of similar kind and quality without deducting depreciation, subject to the policy’s terms and limits.
That difference can become significant when older property is damaged or destroyed.
This guide explains how both methods work, how depreciation affects a claim, and what questions to ask before choosing or reviewing your insurance coverage.
What Is Actual Cash Value?
Actual Cash Value, commonly abbreviated as ACV, generally refers to the value of damaged or destroyed property after accounting for depreciation.
Depreciation reflects the reduction in value associated with factors such as age, wear and tear, and other relevant considerations.
For example, imagine you bought a television for $1,500 several years ago.
If the television is destroyed in a covered loss, it may no longer be considered worth $1,500 for insurance valuation purposes.
Under an ACV approach, the insurer may calculate the property’s value after depreciation.
That can result in a claim payment significantly lower than the cost of buying a new television.
The exact calculation depends on the policy and the circumstances of the loss.
What Is Replacement Cost?
Replacement Cost generally refers to the amount needed to repair or replace damaged property with materials or goods of similar kind and quality, without deducting depreciation, subject to the policy’s terms and limits.
For example, if a covered loss destroys an older television and the policy provides replacement cost coverage for that property, the policy may provide benefits based on the cost of replacing it with a comparable new television.
The policy may have requirements that must be satisfied before the full replacement-cost amount is paid.
For example, some policies may initially pay the property’s actual cash value and then provide additional payment after the property is repaired or replaced and the required documentation is submitted.
This is why you should always read the specific policy rather than assuming that “replacement cost” means the insurer will immediately pay any price for any new item.
ACV vs. Replacement Cost at a Glance
| Feature | Actual Cash Value | Replacement Cost |
|---|---|---|
| Depreciation | Generally deducted | Generally not deducted |
| Potential claim payment | Usually lower for older property | Can be higher |
| Cost to replace older property | May not cover full new replacement cost | Designed to cover replacement cost, subject to policy |
| Premium | May be lower in some policies | May be higher in some policies |
| Requirements | Depends on policy | May require actual repair or replacement |
| Policy limits | Apply | Apply |
| Deductible | May apply | May apply |
The exact terms vary by insurer and policy.
A Simple Example
Suppose a covered loss destroys a five-year-old appliance.
A comparable new appliance costs:
$2,000
The insurer determines that depreciation on the old appliance is:
$800
The simplified calculation under ACV could be:
Replacement cost: $2,000
Minus depreciation: $800
ACV: $1,200
If the policy has a $500 deductible, the simplified claim payment could be:
$1,200 − $500 = $700
Under a replacement-cost policy, the calculation could be different because depreciation is generally not deducted from the replacement cost.
If the policyholder replaces the appliance for $2,000 and meets all applicable policy requirements, the insurer could potentially pay the replacement-cost amount less the applicable deductible and any other limitations.
The actual claim depends on the policy.
This example is intended only to explain the concept.
Why Does Depreciation Matter?
Depreciation can have a major impact on the value assigned to older property.
Imagine that a homeowner has:
- A 10-year-old television
- A 7-year-old washing machine
- A 12-year-old sofa
- A 6-year-old laptop
The amount originally paid for these items does not necessarily represent their current insurance value under an ACV approach.
If the items are destroyed in a covered event, depreciation can reduce the amount used to calculate the claim.
This is why someone may be surprised to discover that the amount they receive under ACV is not enough to purchase brand-new replacements.
Does Replacement Cost Mean You Get the Full Amount Automatically?
Not necessarily.
This is one of the most important details to understand.
Replacement cost coverage does not mean that the insurer will pay any amount you choose to spend.
The policy can contain:
- Coverage limits
- Deductibles
- Conditions
- Exclusions
- Requirements for repairs or replacement
- Limits for certain categories of property
- Special provisions for particular types of damage
For example, the policy may require you to actually repair or replace the damaged property before paying the difference between ACV and replacement cost.
The NAIC notes that some policies initially pay actual cash value and then provide additional replacement-cost benefits after repair or replacement.
Always check your policy documents.
Is Replacement Cost the Same as Market Value?
No.
This is a very common misunderstanding.
Replacement cost is not necessarily the same as the market value of your home.
The market value of a property can be influenced by factors such as:
- Location
- Land value
- Local real estate conditions
- Supply and demand
- Comparable sales
- Neighborhood characteristics
Replacement cost focuses on the cost to repair or rebuild the insured structure with similar materials and quality.
The NAIC specifically distinguishes replacement cost from market value because the two amounts can be substantially different.
Why Your Home’s Replacement Cost Can Differ From Its Market Value
Imagine a house sells for:
$500,000
That does not necessarily mean it would cost $500,000 to rebuild.
The sale price can include the value of the land.
The cost to rebuild the structure could be:
$350,000
or
$650,000
depending on construction costs, labor, materials, location, design, and other factors.
For homeowners insurance, the dwelling coverage amount should generally be based on the estimated cost to rebuild the insured structure rather than simply the home’s market value.
The NAIC advises homeowners to distinguish replacement cost from market value when determining coverage.
How ACV Works for Personal Belongings
ACV can apply to personal property such as:
- Furniture
- Electronics
- Clothing
- Appliances
- Certain household items
Suppose you bought a sofa for $2,000 several years ago.
If its depreciated value at the time of a covered loss is determined to be $700, an ACV policy could value the loss at approximately $700 before any applicable deductible.
That means you might receive substantially less than what you would need to buy a comparable new sofa.
The actual calculation depends on the insurer’s claim evaluation and policy terms.
How Replacement Cost Works for Personal Belongings
Under replacement-cost coverage, the insurer generally calculates the cost of replacing the damaged property with a comparable item, without deducting depreciation, subject to policy conditions.
For example:
Comparable replacement: $2,000
Depreciation: $700
Under ACV:
$2,000 − $700 = $1,300
Under replacement cost:
Potential replacement amount: $2,000
The applicable deductible and other policy provisions still need to be considered.
Some policies may initially pay ACV and later pay the recoverable depreciation after you replace the item.
What Is Recoverable Depreciation?
The term recoverable depreciation may appear during a property insurance claim.
In a simplified example, suppose:
Replacement cost: $10,000
Depreciation: $3,000
ACV: $7,000
If your policy provides replacement-cost coverage and its requirements are met, the insurer might initially pay the ACV amount.
After you repair or replace the property and provide the required documentation, the insurer may pay the additional $3,000 of recoverable depreciation.
The exact process varies by policy.
Not all depreciation is necessarily recoverable.
Your policy determines what is eligible.
Does Replacement Cost Coverage Cost More?
It can.
Replacement-cost coverage generally provides broader financial protection than ACV coverage for property that has depreciated significantly, and that additional protection may result in a higher premium.
The NAIC notes that replacement-cost coverage generally provides more protection but may also cost more than actual cash value coverage.
However, you should not assume that replacement-cost coverage is always a certain percentage more expensive.
Pricing varies according to:
- Insurer
- Location
- Property
- Coverage limits
- Deductible
- Claims history
- Policy characteristics
- Other rating factors
The only reliable way to know the difference is to compare the actual policy options and premiums.
Is Replacement Cost Always Better?
Not necessarily.
It may provide more protection for many homeowners and renters, but the best choice depends on your circumstances, policy options, budget, and the property being insured.
The important question is not simply:
“Which one is better?”
Instead, ask:
“Which type of coverage provides the protection I need at a cost I can afford?”
A cheaper policy can become expensive after a major loss if the coverage does not provide enough money to replace damaged property.
What About the Roof?
Roof coverage deserves special attention.
A homeowner may assume that having replacement-cost coverage means every component of the home will automatically be paid on a full replacement-cost basis.
That is not necessarily true.
Some policies may treat certain parts of a property differently.
The NAIC notes that some policies can apply actual cash value to certain surfaces, such as roofs, while providing replacement-cost coverage for other parts of the home.
This can be especially important for older roofs.
Ask your insurer:
“Is my roof covered at actual cash value or replacement cost?”
Also ask whether different rules apply based on the roof’s age, material, or cause of damage.
What About Valuable Personal Property?
Standard homeowners and renters policies can have specific limits for certain valuable items.
Examples can include:
- Jewelry
- Art
- Collectibles
- Silverware
- Certain electronics
- Antiques
- Other high-value property
If you own expensive items, do not assume that the standard personal-property limit is sufficient.
The NAIC and Triple-I recommend reviewing the limits that apply to valuable possessions and considering additional coverage where appropriate.
You may need to:
- Document the item
- Obtain an appraisal
- Schedule the item
- Purchase an endorsement
- Purchase additional coverage
The requirements depend on the insurer and policy.
ACV vs. RCV: A House Example
Consider a home that suffers $100,000 of covered structural damage.
Suppose the policy’s replacement cost to repair the damage is:
$100,000
The insurer determines that depreciation is:
$20,000
Under a simplified ACV calculation:
$100,000 − $20,000 = $80,000
If the deductible is $2,000:
$80,000 − $2,000 = $78,000
Under replacement-cost coverage, the calculation could potentially be:
$100,000 − $2,000 = $98,000
provided the policy conditions are met and the full amount is covered.
This simplified example illustrates why the difference between ACV and replacement cost can become significant after a major loss.
It does not represent a guaranteed claim payment.
What Is Extended Replacement Cost?
Some homeowners policies may offer Extended Replacement Cost Coverage.
This can provide additional coverage above the dwelling limit when the cost to rebuild exceeds the policy limit, subject to a specified percentage or dollar amount and the policy’s requirements.
For example, a policy might provide an additional percentage above the dwelling coverage limit.
The exact amount and conditions vary by policy.
This coverage can be particularly relevant when construction costs rise unexpectedly after a widespread disaster.
What Is Guaranteed Replacement Cost?
Some policies may offer Guaranteed Replacement Cost Coverage.
This type of coverage can potentially pay the full cost to repair or replace a covered home even if the cost exceeds the stated dwelling limit, subject to the policy’s terms.
The NAIC notes that this type of coverage is uncommon and that policies may contain caps or other conditions.
Do not assume that your homeowners policy includes it.
Check the policy documents.
How to Find Out Which Coverage You Have
You can start with your homeowners or renters insurance policy.
Look for terms such as:
- Actual Cash Value
- ACV
- Replacement Cost
- Replacement Cost Value
- RCV
- Extended Replacement Cost
- Guaranteed Replacement Cost
Check the declarations page and the policy wording.
If the documents are unclear, contact your insurer or insurance professional.
Ask a very specific question:
“If my property is destroyed in a covered loss, will the claim be settled using actual cash value or replacement cost?”
For personal property, ask the same question separately.
You should also ask whether there are different rules for:
- Roofs
- Appliances
- Electronics
- Jewelry
- Furniture
- Other valuable property
Questions to Ask Your Insurance Company
Before purchasing or renewing coverage, consider asking:
1. Is my dwelling covered at replacement cost?
2. Is my personal property covered at replacement cost or actual cash value?
3. Does depreciation apply?
4. Can I recover depreciation after replacing damaged property?
5. Do I have to repair or replace the property to receive the full replacement-cost amount?
6. Are there special rules for my roof?
7. Are there separate limits for valuable personal property?
8. What is my deductible?
9. Are there separate catastrophe deductibles?
10. Are there exclusions that could significantly affect a claim?
Getting answers to these questions before a loss is much easier than discovering the answers after one.
How to Prepare for a Future Claim
One of the best things you can do is create a home inventory.
Document your important possessions.
For each significant item, consider recording:
- Description
- Manufacturer
- Model
- Approximate purchase date
- Purchase price
- Current photographs
- Receipts when available
- Serial number when applicable
Store the information somewhere safe and accessible.
A home inventory can help you understand what you own and provide useful documentation if you need to file a claim.
Triple-I also recommends creating an inventory of personal possessions to help evaluate insurance needs and document property.
Common Mistakes to Avoid
Assuming Market Value Equals Replacement Cost
Your home’s market value and its rebuilding cost can be very different.
Assuming Replacement Cost Means Unlimited Coverage
Replacement cost remains subject to the policy’s limits and conditions.
Ignoring Depreciation
If your policy uses ACV, depreciation can significantly reduce the claim amount.
Not Understanding Your Roof Coverage
A policy may treat certain roof losses differently from other parts of the home.
Forgetting About Valuable Items
Jewelry, art, collectibles, and other expensive possessions may have special limits.
Waiting Until After a Loss to Read the Policy
The best time to understand your coverage is before you need it.
Which Is Better for Renters?
Renters can also encounter the ACV versus replacement-cost distinction.
Suppose a renter’s five-year-old laptop is stolen during a covered event.
Under ACV coverage, depreciation may reduce the amount available for the laptop.
Under replacement-cost coverage, the policy may provide benefits based on the cost of a comparable replacement, subject to the policy terms.
Renters should check whether their personal property coverage is ACV or replacement cost.
Frequently Asked Questions
Is actual cash value the same as market value?
Not necessarily.
ACV generally accounts for depreciation when determining the value of damaged or destroyed property.
Market value refers to what an asset could sell for in a market and can involve different considerations.
For homeowners insurance, replacement cost and market value are not the same concept.
Is replacement cost the same as the original purchase price?
No.
Replacement cost generally refers to the cost of replacing or repairing the property with comparable materials or goods at the time of the loss, subject to the policy.
The current replacement cost could be higher or lower than the original purchase price.
Does replacement cost include depreciation?
Generally, replacement-cost coverage does not deduct depreciation from the covered replacement cost, subject to the policy’s terms.
Can I have ACV for some property and replacement cost for other property?
Yes.
Different types of property or different parts of a policy can be subject to different valuation provisions.
Always check the specific policy.
Does replacement cost cover my home’s land?
Generally, homeowners dwelling insurance is focused on the insured structure rather than the market value of the land.
The cost to rebuild the structure and the property’s market value are different concepts.
Can replacement cost exceed my policy limit?
Normally, the standard replacement-cost coverage is subject to the applicable policy limit.
Some policies may provide extended or guaranteed replacement-cost features with additional protection.
Check your policy.
Does a deductible still apply to replacement-cost coverage?
Yes, a deductible can still apply.
Replacement cost does not mean the insurer automatically pays the entire repair or replacement bill.
Bottom Line
The difference between Actual Cash Value and Replacement Cost can have a major impact on what you receive after a covered insurance loss.
Actual Cash Value generally accounts for depreciation.
Replacement Cost generally does not deduct depreciation from the covered replacement cost, subject to policy terms, limits, and conditions.
For older property, the difference can be substantial.
Before buying or renewing homeowners or renters insurance, determine which valuation method applies to your home and personal belongings.
Then check your deductible, coverage limits, exclusions, roof provisions, and any special limits for valuable property.
The cheapest policy is not necessarily the policy that provides the most useful protection when you actually need to file a claim.
Sources and Further Reading
- National Association of Insurance Commissioners (NAIC) — What’s the Difference Between Actual Cash Value Coverage and Replacement Cost Coverage?
- National Association of Insurance Commissioners — A Consumer’s Guide to Home Insurance
- National Association of Insurance Commissioners — Post-Disaster Claims Guide
- Insurance Information Institute (Triple-I) — How Is the Settlement Amount Determined?
- Insurance Information Institute — How Much Homeowners Insurance Do I Need?
Editorial Review
Reviewed by the Insurances Claims Editorial Team
This article was prepared for general educational purposes using publicly available information from insurance regulators and established insurance education organizations.
Insurance coverage, valuation methods, claim procedures, deductibles, exclusions, and policy requirements vary by insurer, state, policy, and individual circumstances.
Last reviewed: September 2026
Insurance Disclaimer
The information provided by Insurances Claims is for general educational purposes only. It is not insurance, financial, legal, tax, or professional advice and does not create an insurance contract.
Always review your actual policy documents and contact your insurer, licensed insurance professional, or appropriate regulatory authority for guidance regarding your specific circumstances.